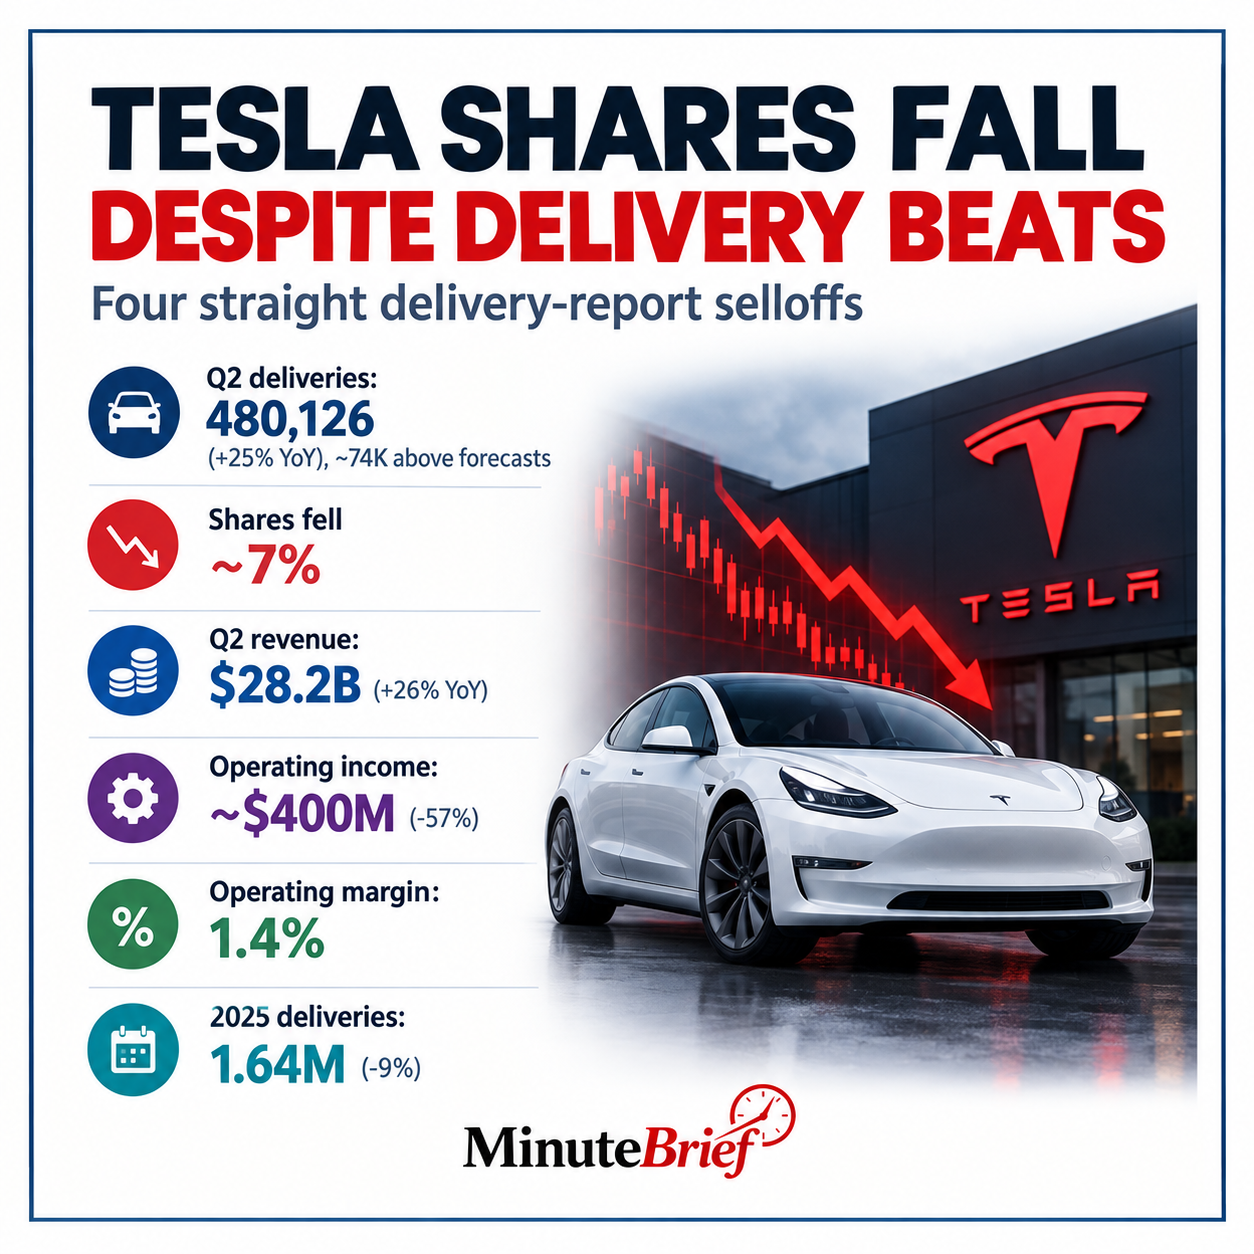
Tesla shares have fallen following each of the company's last four quarterly delivery reports, despite exceeding analyst expectations. On July 2, Tesla reported 480,126 second-quarter deliveries, approximately 74,000 above forecasts, yet the stock dropped about 7%.
During these report days, the broader S&P 500 remained nearly flat, indicating the negative reaction was specific to Tesla.This pattern began in October 2025 when Tesla delivered a record 497,099 vehicles, but shares declined about 5%. In January 2026, fourth-quarter deliveries fell 16% year over year to 418,227, accompanied by a roughly 3% stock decline.
April deliveries rose 6% year over year to 358,023, while shares fell over 5%. July saw a 25% year-over-year increase to 480,126 deliveries, yet the stock experienced the sharpest decline among these report days. The repeated selloffs suggest investors are focusing beyond delivery totals, emphasizing profitability and growth quality. In the second quarter, Tesla’s revenue increased 26% year over year to about $28.2 billion, but operating income dropped 57% to approximately $400 million.
Operating margin narrowed to 1.4% from 5.8% in the third quarter of 2025, marking three consecutive quarters of margin compression. Tesla’s overall delivery performance has also faced challenges. Its 2025 annual deliveries declined about 9% to 1,636,129 vehicles, marking the company’s second consecutive annual decline. With another delivery report expected in early October, investors will closely watch both delivery volumes and whether higher numbers can support stronger operating profitability.