The Indian government’s decision to raise the Employees' Provident Fund Organisation (EPFO) wage ceiling from ₹15,000 to ₹25,000 marks a significant shift in the country’s formal social security system. It was announced by the Labour Ministry on September 16, 2026, and followed by EPFO FAQs, the change broadens the salary base subject to mandatory provident fund contributions.
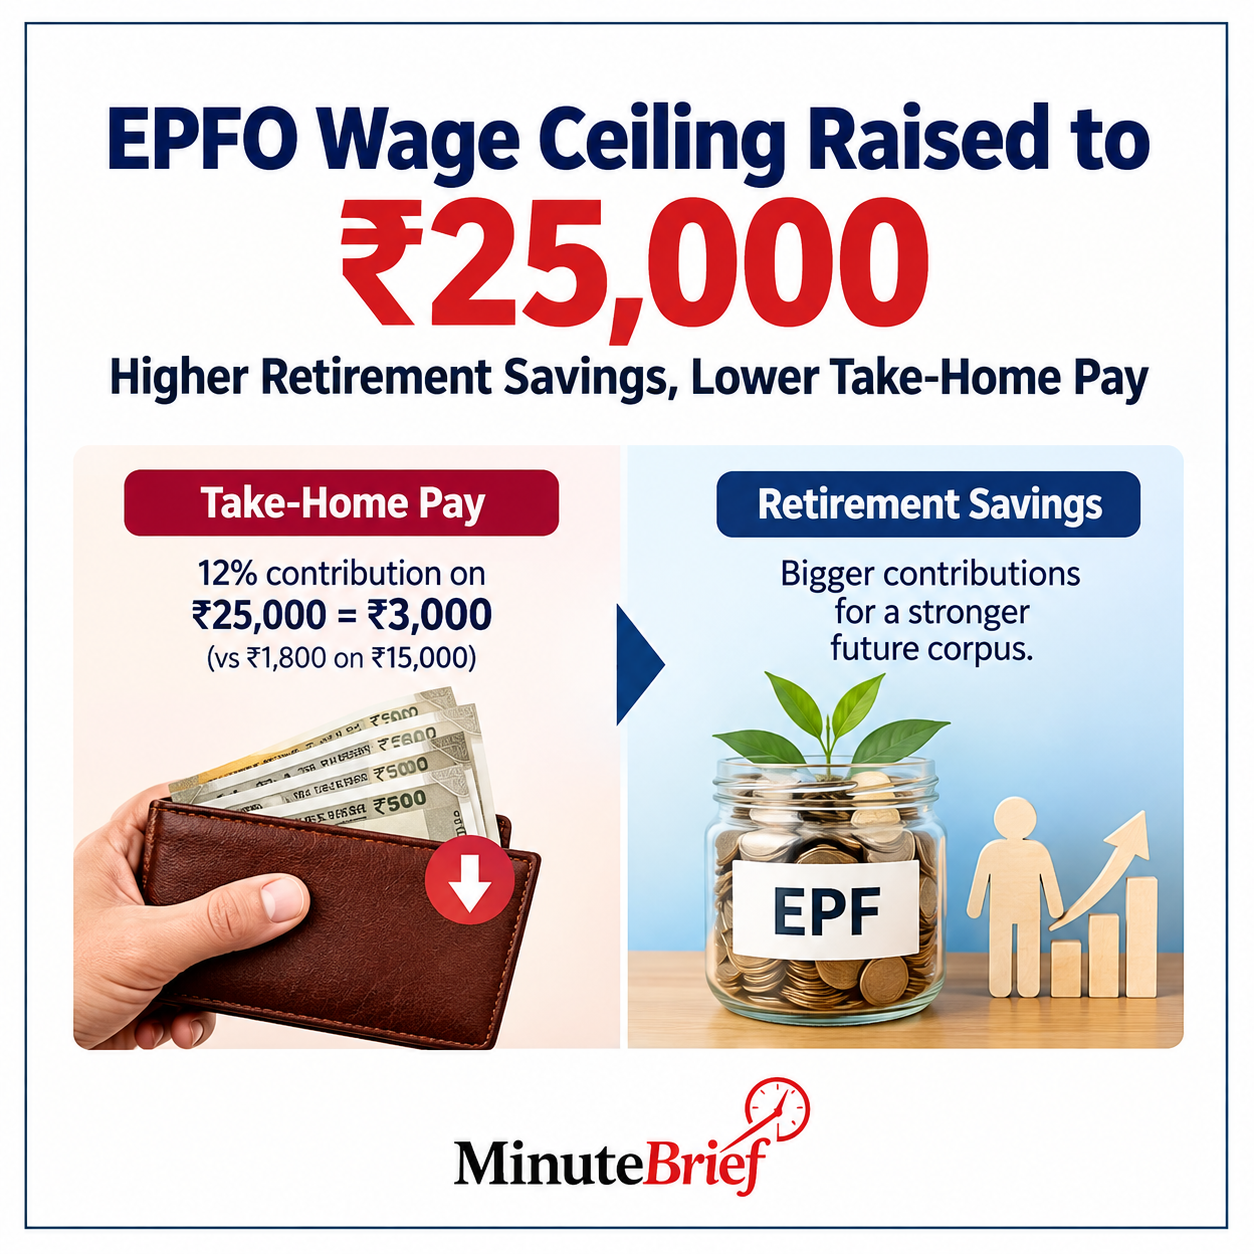
For employees, this means higher monthly deductions for retirement savings. For example, at 12%, contributions rise from ₹1,800 to ₹3,000, reducing take-home pay by ₹1,200. This reduction can affect workers managing essential expenses like rent, school fees, and loans, highlighting a shift in the balance between current income and future financial security.
However, increased contributions also build larger retirement savings, as employers contribute alongside employees, promoting systematic saving over voluntary efforts later in life. The previous ceiling was set in 2014; with economic changes since, the update reflects shifts in wages and living costs. Still, the reform does not fully address retirement insecurity, given India’s diverse workforce and varying impacts on individuals' budgets.
Clear communication is essential to help employees understand if and how the new ceiling affects their contributions and employers’ contributions to their provident funds.
Differentiating statutory contributions from voluntary or other provident fund arrangements is also important, as higher contributions may involve specific rules beyond the basic ceiling.
The reform should be neither alarmed nor uncritically celebrated. Its key argument is that retirement security should grow with wages, ensuring more earnings are captured in organized savings. Its main concern is that mandatory long-term saving might constrain short-term financial flexibility.
Ultimately, success depends on whether workers gain better financial understanding and stronger retirement security without undue stress on current finances.
A provident fund represents a promise to one’s future self, challenging policymakers to balance that promise without burdening workers today.
The ₹25,000 ceiling underscores a core economic dilemma: how much to sacrifice now for a stable tomorrow. This balance will vary between households, but transparency, informed choice, and clear knowledge of contribution allocations should remain constant.