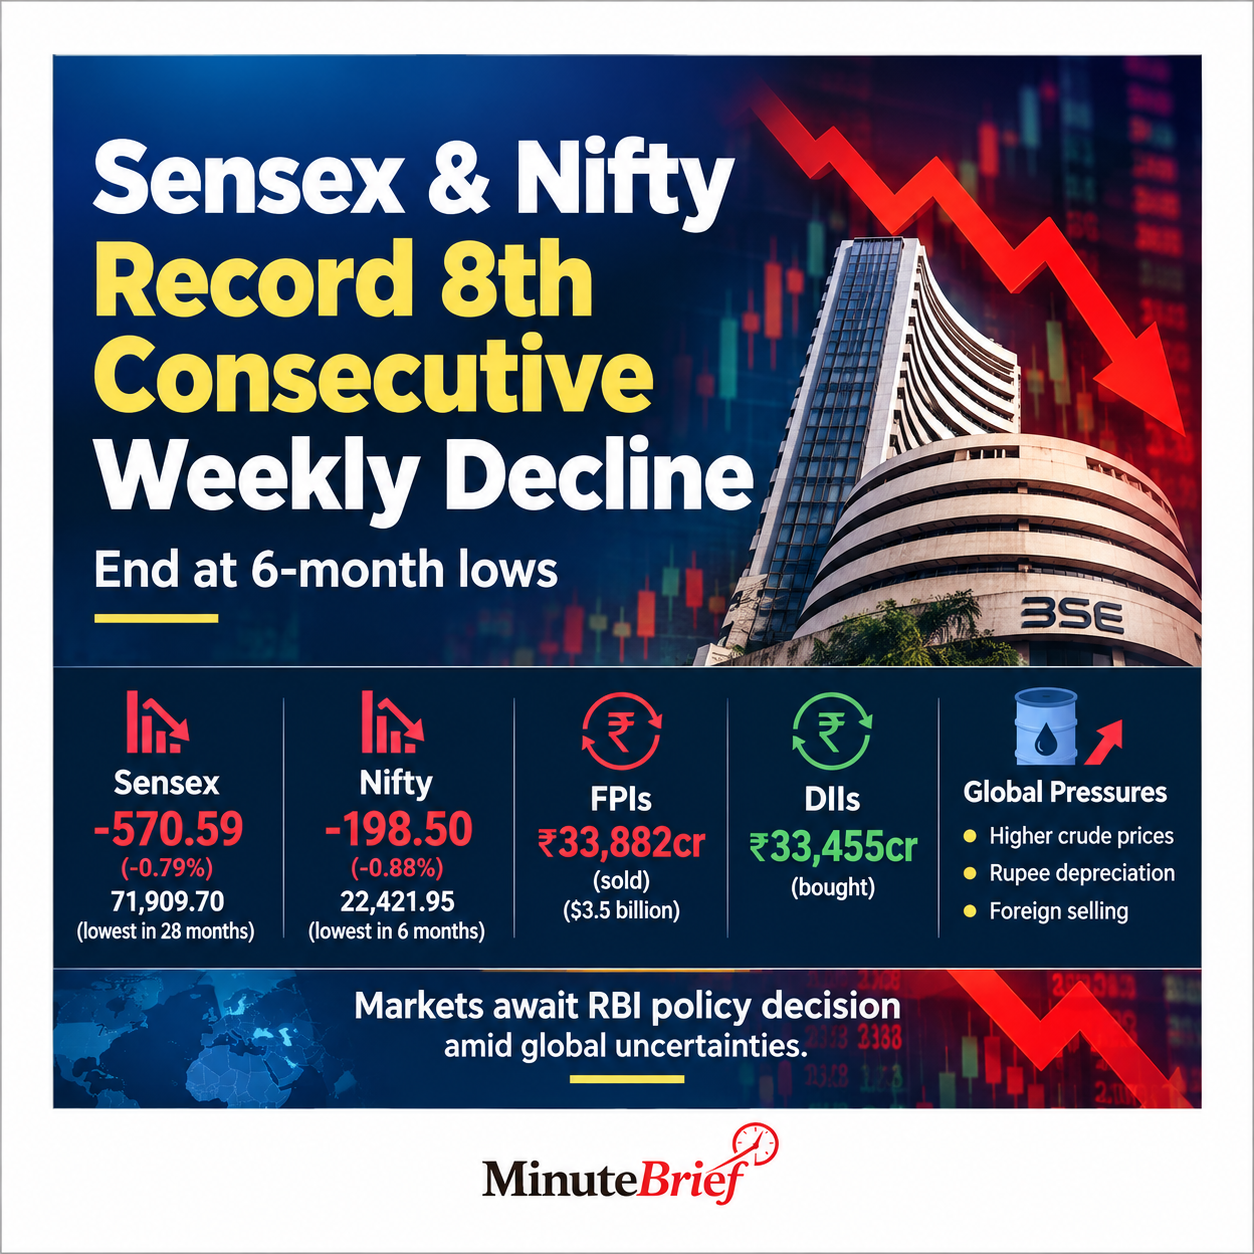
Indian stock markets extended their decline to an eighth consecutive week, marking the longest losing streak in 25 years. On October 1, 2026, the Sensex dropped 570.59 points, or 0.79%, closing at 71,909.70—the lowest in 28 months. The Nifty fell 198.50 points, or 0.88%, ending at 22,421.95, its lowest close in six months.
Despite recovering more than half of their intraday losses, persistent selling pressure dampened investor sentiment. The weekly performance underscored the market’s weakness, with the Sensex declining 2.69% and the Nifty down 3.11%. Broader indices also suffered significant losses: the BSE Midcap fell 3.65%, and the Smallcap index dropped 2.64%.
Selling was notable in consumer durables, public-sector banks, real estate, and metal stocks. Automobile shares faced pressure following weak wholesale sales data. Information technology stocks were the only sectoral gainers, buoyed by the rupee's depreciation.
Several global factors contributed to the decline. Rising crude oil prices heightened concerns about India’s import costs and inflation. Simultaneously, U.S. Treasury yields neared their highest levels in nearly two decades amid expectations of further Federal Reserve tightening.
Higher U.S. yields can attract capital to American assets, pressuring emerging markets and reducing foreign demand for Indian equities. Additionally, the narrowing interest-rate gap between India and the U.S. weighed on the rupee. Foreign portfolio investors (FPIs) sold Indian shares worth ₹33,882 crore (about $3.5 billion) during the week. Domestic institutional investors (DIIs) bought shares worth ₹33,455 crore, absorbing much of the foreign selling.
However, domestic buying was insufficient to halt the market’s decline. The downturn reduced the total market capitalisation of BSE-listed firms from ₹481.9 lakh crore to ₹467 lakh crore, eroding roughly ₹15 lakh crore in investor wealth. Focus now shifts to the Reserve Bank of India’s upcoming monetary policy decision.
Policymakers face the challenge of balancing inflation risks, currency depreciation, and global financial uncertainty. Higher crude prices could elevate imported inflation, while rising international interest rates may intensify capital outflows.
The RBI’s response will be closely watched by investors seeking clarity on the economic outlook. The sustained market decline highlights the impact of global developments on domestic financial markets. While institutional buying has provided some support, ongoing foreign selling and oil price volatility continue to test investor confidence.
A recovery will depend on improvements in global conditions, currency stability, investment flows, and corporate earnings. Until then, volatility is expected to remain a significant concern for Indian equity markets.